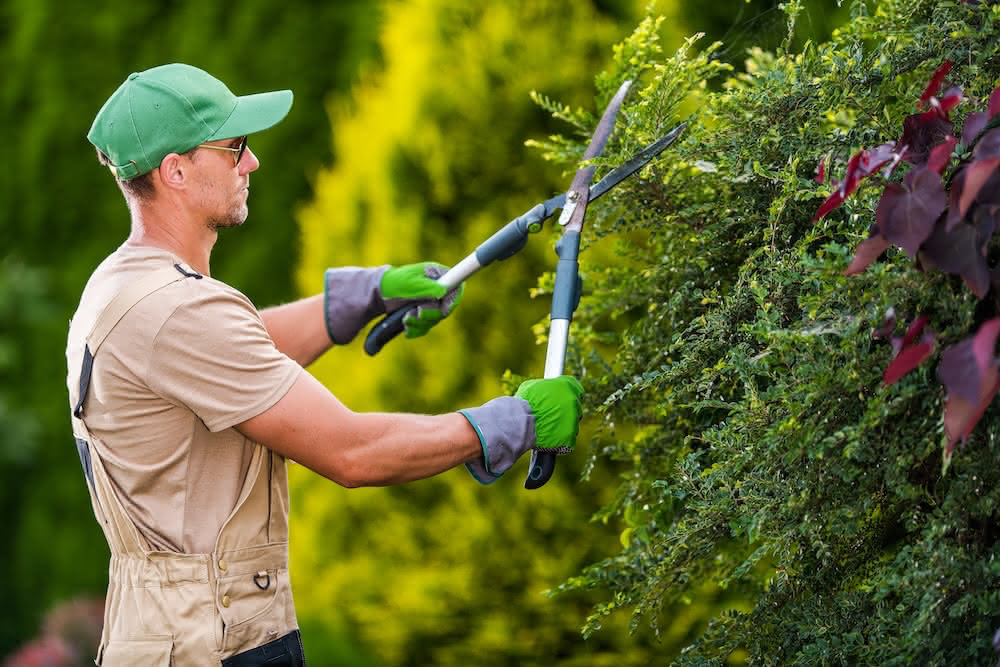
A landscaping contractor was on a strong growth trajectory, adding contracts and expanding its portfolio at a pace that had revenue doubling within the year. The model was working. The problem was structural: landscaping gets paid after the work is done, which means every new contract requires spending before earning. A challenged credit score had already closed the conventional lending window. Growth was stalling not because of demand, but because of access to capital.
Vision
Double revenue within the year. That was the target, and it was achievable. The pipeline was real, the crew was capable, and the contracts were there to be won. What the business needed was a lender willing to evaluate the opportunity rather than stop at a credit score.
Opportunity
The available contracts would not stay available. Competitors were watching the same pipeline. Securing working capital quickly meant securing work that would otherwise go elsewhere. Speed here was not a preference. It was the difference between growing and staying flat.
Challenge

Credit Score Barrier
A challenged score stopped most lenders before they even looked at the revenue, the contracts, or the trajectory. The business could not get a fair review through traditional channels.
Upfront Costs, Delayed Pay
Labor, materials, and equipment had to be committed before any client payment came in. Without working capital, each new contract was a cash flow risk rather than an opportunity.
Contracts at Risk
The window to win new work was open, but not indefinitely. Every day without funding was a day a competitor could step in.

How Fora Financial Helped
Fora Financial set the credit score aside and evaluated what was actually there. Strong revenue, active contracts, a clear plan. The $100,000 in working capital arrived quickly and went directly toward covering the upfront project costs that had been limiting how much new work the business could take on.
Results

New Contracts Secured
With capital available, the contractor took on projects that would have been out of reach without working capital in place.

Cash Flow Stabilized
Day-to-day expenses stayed covered as the business grew, without the team having to manage cash gaps alongside managing jobs.

Built to Scale
The funding gave the business the foundation it needed to keep growing rather than hitting a ceiling every time a new contract required upfront spend.
Conclusion
A credit score is one data point. Fora Financial looked at the whole picture, found a business worth backing, and delivered capital that let the contractor pursue the growth it had already put in motion.
Why Fora Financial
-
No Red Tape
Fora Financial moved quickly and without the friction that had blocked every conventional option.
-
Looked Beyond the Score
The underwriting process focused on what the business was actually doing, not just what a credit report said about it.
-
Capital When It Counted
Funding arrived while the contracts were still available to win.